Renewable energy has moved from a climate-policy sector into a core industrial, infrastructure and energy-security market.
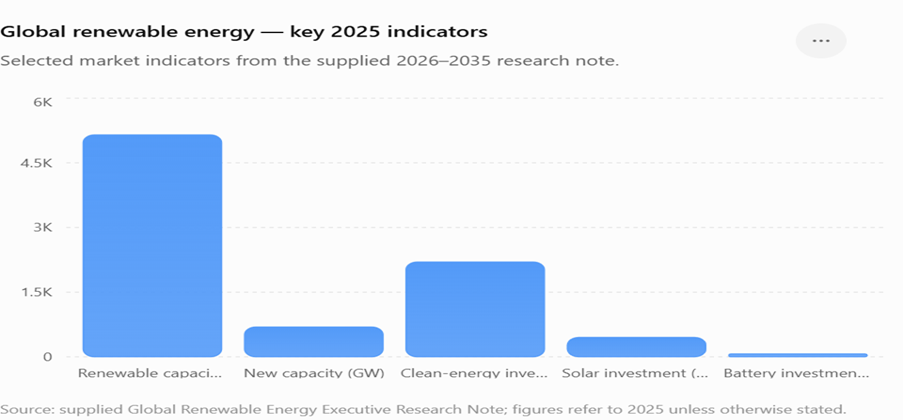
Global renewable power capacity reached 5,149 GW at end-2025.
After a record 692 GW addition in 2025.
Renewables represented 85.6% of all new power capacity in 2025.
IEA expects approximately 4,600 GW of additional renewable capacity during 2025–2030.
IEA expects approximately 4,600 GW of additional renewable capacity during 2025–2030, roughly twice the deployment of 2019–2024.
Solar PV alone is expected to account for almost 80% of renewable electricity expansion.
Distributed PV represents about 42% of PV growth.
Additional capacity expected during 2025–2030
An evolving ecosystem connecting clean generation, grid infrastructure, energy storage and electrification.
Investment is increasingly moving toward an integrated renewables + grids + storage + electrification + low-carbon fuels ecosystem.
Global energy investment is expected to reach $3.3 trillion in 2025.
About $2.2 trillion in clean-energy technologies, approximately twice fossil-fuel investment.
Solar investment alone is estimated at $450 billion.
Battery-storage investment approaches $66 billion.
Key dimensions shaping the 2026–2035 outlook
| Dimension | 2026–2035 outlook |
|---|---|
| Dominant technologies | Solar PV, onshore wind, batteries, hydropower/pumped storage |
| Fast-emerging | Green hydrogen, offshore wind, advanced geothermal, long-duration storage |
| Enabling infrastructure | Transmission, distribution, smart grids, power electronics, digital energy |
| Industrial opportunity | Manufacturing, EPC, O&M, recycling, critical minerals, energy software |
| Demand drivers | Electrification, AI/data centres, EVs, cooling, industrial decarbonisation, energy security |
| Major geographic engines | China, EU, US, India, Middle East, Southeast Asia, Latin America and Africa |